
Investment Weekly: Bonds hedging again?
26 October 2026
Key takeaways
-
The recent AI-induced tech sell-off was a sharp reminder that relentless outperformance breeds fragility. Since 2011, the cap-weighted S&P 500 has trounced its equal-weighted cousin by nearly 225%, with just ten stocks commanding close to 40% of the index. Despite a modest de-rating this year, mega-cap tech remains hypersensitive to shifts in AI sentiment.
-
UK Chancellor Healey heads into this week’s Budget buoyed by IMF praise for a commitment to fiscal discipline. The numbers look good: the Fund sees the budget balance stripping out cyclical effects and interest payments (the so-called “structural primary” balance) moving into surplus in 2028 for the first time since 2001.
-
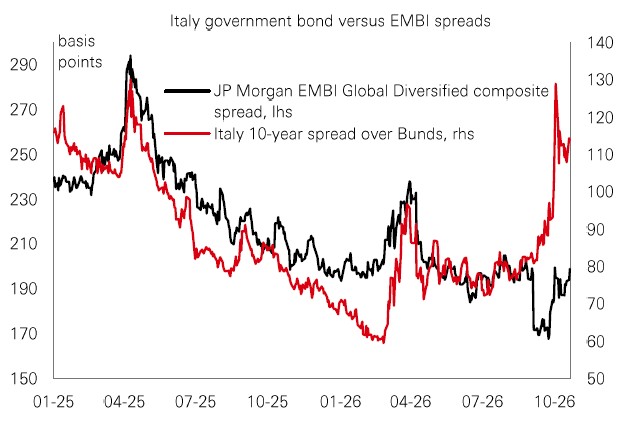
The big market stories of 2026 have centred on the relentless AI boom and the sell-off in Western government bonds. Yet, flying under the radar is just how well-behaved hard-currency emerging market debt (EMD) spreads have been.
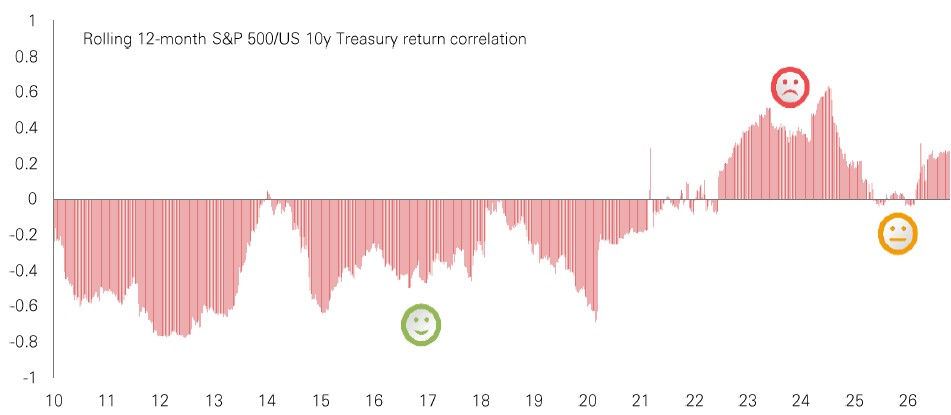
Chart of the week – Bonds hedging again?
For those worried about the AI boom turning to bust, the recent market action offered a glimpse of how things could unfold. As investors dumped assets perceived as vulnerable to the AI story souring, there were some obvious underperformers: namely, chip-heavy indices in South Korea and Taiwan, and the Nasdaq. But it’s how other assets moved that provides some useful signals on how investors can protect themselves. Three things stand out:
#1 There was a rotation to old-economy, value, or domestically focused indices such as those in the UK, the eurozone, and India. Having lagged during the AI boom, these low-tech markets may provide natural shelters during a tech pullback (see Market Spotlight below).
#2 Elsewhere, a fall in the US dollar lends weight to the idea that the currency has lost some of its shine as a haven asset. It also implies that the issue of dollar hedging in portfolios needs to be taken seriously.
#3 But it was action in the bond market that provided the most important signal of all. After years of investors questioning the ability of bonds to hedge portfolios during stock market sell-offs, Treasuries came to the rescue this time around, with yields across the curve falling sharply.
With starting yields now higher, bonds offer enticing income opportunities. And their ability to hedge against a big tech sell-off or growth scare is a major bonus. But the world is complex, and inflation shocks are still likely. This means we can’t over-rely on a single diversifier – high-quality credit, commodities, emerging markets, real assets, and alternative assets all have a role to play.
Market Spotlight
Sensex appeal
Sitting out the AI boom has made 2026 a bruising year for Indian equities. Because AI themes make up just 14.5% of the market – versus over 80% in Taiwan and nearly three-quarters in South Korea – foreign investors have ditched India for chip-heavy hubs, inflicting the market’s longest relative losing streak in 25 years.
Yet, amid the recent tech rout, India’s economy is thriving. GDP grew 7.8% year-on-year in Q2, while corporate profits jumped by 11.4%. Firms have slashed debt, growth is less oil-intensive, and households sit on USD 3.9trn of gold – double its value two years ago – which they are increasingly borrowing against to fund spending.
This year’s sell-off has also stripped away India's usual valuation premium. Price-to-book multiples now sit below their 10-year average, and at a 20-year low relative to emerging-market peers.
The value of investments and any income from them can go down as well as up and investors may not get back the amount originally invested. The level of yield is not guaranteed and may rise or fall in the future. Past performance does not predict future returns. For informational purposes only and should not be construed as a recommendation to invest in the specific company, country, product, strategy, sector, or security. Diversification does not ensure a profit or protect against loss. Any views expressed were held at the time of preparation and are subject to change without notice. Any forecast, projection or target where provided is indicative only and is not guaranteed in any way. Index returns assume reinvestment of all distributions and do not reflect fees or expenses. You cannot invest directly in an index. Source: HSBC Asset Management, Factset, Bloomberg, Macrobond. Data as at 7.30am UK time 23 October 2026.
Lens on…
Heavy lies the crown
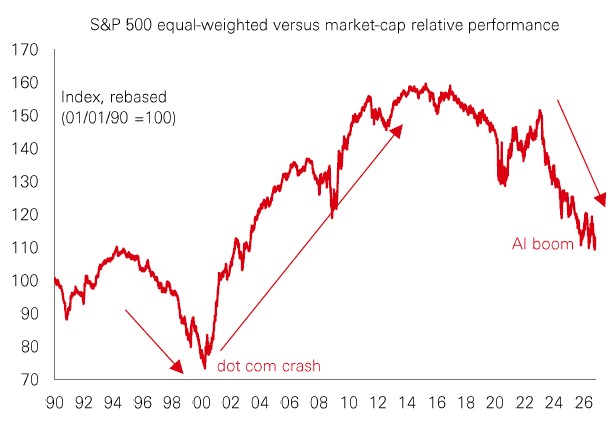
The recent AI-induced tech sell-off was a sharp reminder that relentless outperformance breeds fragility. Since 2011, the cap-weighted S&P 500 has trounced its equal-weighted cousin by nearly 225%, with just ten stocks commanding close to 40% of the index. Despite a modest de-rating this year, mega-cap tech remains hypersensitive to shifts in AI sentiment. The equal-weighted index’s steep relative slump during the AI boom echoes the late-1990s dot-com mania. If AI hits a genuine roadblock further down the line, history favours the underdogs: in the five years after the 2000 bubble burst, the equal-weighted index outperformed its cap-weighted counterpart by around 50%. Yet investors need not bet on an AI bust to look elsewhere. Even if the tech story holds, AI spillovers—alongside broadening capex—should lift left-behind sectors and smaller-cap names across Industrials and Financials. Nasdaq earnings growth is forecast to more than halve in 2027, while equal-weight valuations sit at an enticing 15x. |
The most compelling opportunities now lie beyond the mega-caps—leaving globally diversified portfolios across sectors, regions, and market caps well positioned for the coming years.
2001: A fiscal odyssey
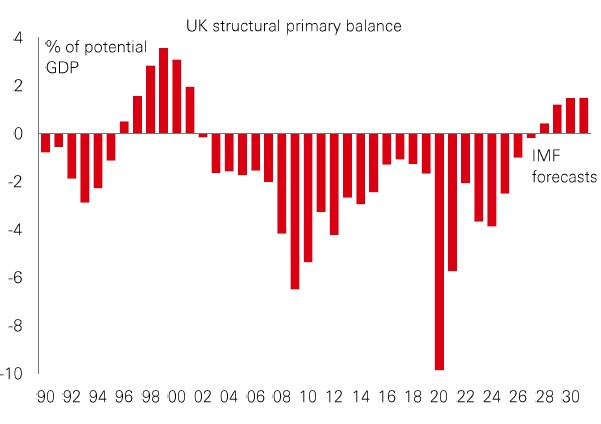
UK Chancellor Healey heads into this week’s Budget buoyed by IMF praise for a commitment to fiscal discipline. The numbers look good: the Fund sees the budget balance stripping out cyclical effects and interest payments (the so-called “structural primary” balance) moving into surplus in 2028 for the first time since 2001. But the journey back to the fiscal health of 2001 will be arduous. The UK has previously delivered prolonged fiscal tightening, notably during the mid-to-late 1990s and following the Global Financial Crisis. However, the 1990s journey was propelled by average growth of more than 3% – over twice the pace projected by the IMF for the coming years. And the post-crisis austerity period was politically challenging and uneven. |
Having failed to restrain spending in 2024, the government has left tax rises to carry the load. Yet, with the tax burden already near multi-decade highs, further increases risk diminishing returns. Gilts provide decent income opportunities right now, but difficulties in reaching firmer fiscal ground imply sticky yields and limited scope for capital gains outside of a major downturn.
Spread the word
The big market stories of 2026 have centred on the relentless AI boom and the sell-off in Western government bonds. Yet, flying under the radar is just how well-behaved hard-currency emerging market debt (EMD) spreads have been. Historically, riskier European sovereigns like Italy moved in lockstep with emerging markets. Recently, however, a striking disconnect has opened up: the yield gap between Italian government bonds and German Bunds has widened sharply, whereas EMD has traded more like a relative haven. What explains this divergence? While Western governments grapple with poor fiscal dynamics, weak growth, and higher interest rates, some EMs are reaping the rewards of broad structural improvements. Robust institutions, deeper local capital markets, and better crisis management have fortified fundamentals. |
Prudent monetary policy has provided a further buffer. By acting early to tame inflation, some EM central banks have fostered currency stability, making it easier to service external debt.
Past performance does not predict future returns. The level of yield is not guaranteed and may rise or fall in the future. For informational purposes only and should not be construed as a recommendation to invest in the specific country, product, strategy, sector, or security. Diversification does not ensure a profit or protect against loss. Any views expressed were held at the time of preparation and are subject to change without notice. Index returns assume reinvestment of all distributions and do not reflect fees or expenses. You cannot invest directly in an index. Any forecast, projection or target where provided is indicative only and is not guaranteed in any way. Source: HSBC Asset Management. Macrobond, Bloomberg, Refinitiv, FactSet. Data as at 7.30am UK time 23 October 2026.
Key Events and Data Releases
Last week

This week

For informational purposes only and should not be construed as a recommendation to invest in the specific country, product, strategy, sector or security. Any views expressed were held at the time of preparation and are subject to change without notice. Any forecast, projection or target where provided is indicative only and is not guaranteed in any way. Index returns assume reinvestment of all distributions and do not reflect fees or expenses. You cannot invest directly in an index. Source: HSBC Asset Management. Data as at 7.30am UK time 23 October 2026.
Market review
Global equity markets struggled to make headway amid rising AI growth concerns and higher oil prices. US equities were mixed as investors digested Q3 tech earnings. The S&P 500 and small-cap Russell 2000 posted modest gains. The Nasdaq traded sideways, with investors rotating from AI stocks towards value and defensive sectors, including Consumer Staples. The Euro Stoxx 50 fell on rising growth concerns. Asian bourses saw widespread losses due to lower tech stocks. The Hang Seng and Kospi indices weakened in choppy trading. The Shanghai Composite retreated on fading optimism about fiscal stimulus. The Nikkei 225 index fell. Frontier markets were resilient. In rates, 10yr Treasury yields fell ahead of the Federal Reserve meeting. Ongoing fiscal and political concerns raised 10yr French OAT yields. The US dollar softened against most of its major peers.
Share


Achieve your wealth goals with our suite of wealth management solutions

Open an investment account and start your wealth journey with us
Related Insights


Disclaimer
This document or video is prepared by The Hongkong and Shanghai Banking Corporation Limited (‘HBAP’), 1 Queen’s Road Central, Hong Kong. HBAP is incorporated in Hong Kong and is part of the HSBC Group. This document or video is distributed and/or made available by HSBC Bank (China) Company Limited, HSBC Bank (Singapore) Limited, HSBC Bank Middle East Limited (UAE), HSBC UK Bank Plc, HSBC Bank Malaysia Berhad (198401015221 (127776-V))/HSBC Amanah Malaysia Berhad (20080100642 1 (807705-X)), HSBC Bank (Taiwan) Limited, HSBC Bank plc, Jersey Branch, HSBC Bank plc, Guernsey Branch, HSBC Bank plc in the Isle of Man, HSBC Continental Europe, Greece, The Hongkong and Shanghai Banking Corporation Limited, India (HSBC India), HSBC Bank (Vietnam) Limited, PT Bank HSBC Indonesia (HBID), HSBC Bank (Uruguay) S.A. (HSBC Uruguay is authorised and oversought by Banco Central del Uruguay), The Hongkong and Shanghai Banking Corporation Limited – Philippine Branch, HSBC Investment and Insurance Brokerage, Philippines Inc, HSBC Insurance Brokerage Company Limited, HSBC Mexico, S.A. Multiple Banking Institution HSBC Financial Group (collectively, the “Distributors”) and HSBC Bank Middle East Limited Qatar Branch, P.O. Box 57, Doha, Qatar (regulated by Qatar Central Bank for the purpose of this promotion and lead regulated by the Dubai Financial Services Authority) to their respective clients. This document or video is for general circulation and information purposes only.
The contents of this document or video may not be reproduced or further distributed to any person or entity, whether in whole or in part, for any purpose. This document or video must not be distributed in any jurisdiction where its distribution is unlawful. All non-authorised reproduction or use of this document or video will be the responsibility of the user and may lead to legal proceedings. The material contained in this document or video is for general information purposes only and does not constitute investment research or advice or a recommendation to buy or sell investments. Some of the statements contained in this document or video may be considered forward looking statements which provide current expectations or forecasts of future events. Such forward looking statements are not guarantees of future performance or events and involve risks and uncertainties. Actual results may differ materially from those described in such forward-looking statements as a result of various factors. HBAP and the Distributors do not undertake any obligation to update the forward-looking statements contained herein, or to update the reasons why actual results could differ from those projected in the forward-looking statements. This document or video has no contractual value and is not by any means intended as a solicitation, nor a recommendation for the purchase or sale of any financial instrument in any jurisdiction in which such an offer is not lawful. The views and opinions expressed are based on the HSBC Global Investment Committee at the time of preparation and are subject to change at any time. These views may not necessarily indicate HSBC Asset Management‘s current portfolios’ composition. Individual portfolios managed by HSBC Asset Management primarily reflect individual clients’ objectives, risk preferences, time horizon, and market liquidity.
The value of investments and the income from them can go down as well as up and investors may not get back the amount originally invested. Past performance contained in this document or video is not a reliable indicator of future performance whilst any forecasts, projections and simulations contained herein should not be relied upon as an indication of future results. Where overseas investments are held the rate of currency exchange may cause the value of such investments to go down as well as up. Investments in emerging markets are by their nature higher risk and potentially more volatile than those inherent in some established markets. Economies in emerging markets generally are heavily dependent upon international trade and, accordingly, have been and may continue to be affected adversely by trade barriers, exchange controls, managed adjustments in relative currency values and other protectionist measures imposed or negotiated by the countries with which they trade. These economies also have been and may continue to be affected adversely by economic conditions in the countries in which they trade. Investments are subject to market risks, read all investment related documents carefully.
This document or video provides a high-level overview of the recent economic environment and has been prepared for information purposes only. The views presented are those of HBAP and are based on HBAP’s global views and may not necessarily align with the Distributors’ local views. It has not been prepared in accordance with legal requirements designed to promote the independence of investment research and is not subject to any prohibition on dealing ahead of its dissemination. It is not intended to provide and should not be relied on for accounting, legal or tax advice. Before you make any investment decision, you may wish to consult an independent financial adviser. In the event that you choose not to seek advice from a financial adviser, you should carefully consider whether the investment product is suitable for you. You are advised to obtain appropriate professional advice where necessary.
The accuracy and/or completeness of any third-party information obtained from sources which we believe to be reliable might have not been independently verified, hence customers must seek several sources prior to making investment decisions.
The following statement is only applicable to HSBC Mexico, S.A. Multiple Banking Institution HSBC Financial Group with regard to how the publication is distributed to its customers: This publication is distributed by Wealth Insights of HSBC México, and its objective is for informational purposes only and should not be interpreted as an offer or invitation to buy or sell any security related to financial instruments, investments or other financial product. This communication is not intended to contain an exhaustive description of the considerations that may be important in making a decision to make any change and/or modification to any product, and what is contained or reflected in this report does not constitute, and is not intended to constitute, nor should it be construed as advice, investment advice or a recommendation, offer or solicitation to buy or sell any service, product, security, merchandise, currency or any other asset.
Receiving parties should not consider this document as a substitute for their own judgment. The past performance of the securities or financial instruments mentioned herein is not necessarily indicative of future results. All information, as well as prices indicated, are subject to change without prior notice; Wealth Insights of HSBC Mexico is not obliged to update or keep it current or to give any notification in the event that the information presented here undergoes any update or change. The securities and investment products described herein may not be suitable for sale in all jurisdictions or may not be suitable for some categories of investors.
The information contained in this communication is derived from a variety of sources deemed reliable; however, its accuracy or completeness cannot be guaranteed. HSBC México will not be responsible for any loss or damage of any kind that may arise from transmission errors, inaccuracies, omissions, changes in market factors or conditions, or any other circumstance beyond the control of HSBC. Different HSBC legal entities may carry out distribution of Wealth Insights internationally in accordance with local regulatory requirements.
Important Information about the Hongkong and Shanghai Banking Corporation Limited, India (“HSBC India”): HSBC India is a branch of The Hongkong and Shanghai Banking Corporation Limited. HSBC India does not distribute or refer investment products to those persons who are either the citizens or residents of United States of America (USA), Canada or any other jurisdiction where such distribution or referral would be contrary to law or regulation.
HSBC India is an AMFI-registered Mutual Fund Distributor and an AMFI-registered Specialized Investment Fund (SIF) Distributor. HSBC India distributes select mutual fund schemes and SIF strategies of empaneled Asset Management Companies, and acts as a referrer of other third-party investment products. Mutual Fund investments are subject to market risks, read all scheme-related documents carefully. AMFI-registered Mutual Fund Distributor | Date of Initial Registration: 19 Feb 2002 | ARN-0022 I Validity of ARN: 18 Feb 2027. AMFI-registered SIF Distributor I Date of initial registration: 27 Oct 2025 | ARN-0022 I Validity of ARN: 26 Oct 2028.
HSBC India will receive commission from HSBC Asset Management (India) Private Limited, in its capacity as a AMFI registered mutual fund distributor of HSBC Mutual Fund. The Sponsor of HSBC Mutual Fund is HSBC Securities and Capital Markets (India) Private Limited (HSCI), a member of the HSBC Group. Please note that HSBC India and the Sponsor being part of the HSBC Group, may give rise to real, perceived, or potential conflicts of interest. HSBC India has a policy in place to identify, prevent and manage such conflict of interest. For more information related to investments in the securities market, please visit the SEBI Investor Website: https://investor.sebi.gov.in/ and the SEBI Saa₹thi Mobile App.
The following statement is only applicable to HSBC Bank (Taiwan) Limited with regard to how the publication is distributed to its customers: HSBC Bank (Taiwan) Limited (“the Bank”) shall fulfill the fiduciary duty act as a reasonable person once in exercising offering/conducting ordinary care in offering trust services/ business. However, the Bank disclaims any guarantee on the management or operation performance of the trust business.
The following statement is only applicable to PT Bank HSBC Indonesia (“HBID”): HBID is licensed and supervised by Indonesia Financial Services Authority (“OJK”). Investment products that are offered in HBID are third party products, HBID is a selling agent for third party products such as Mutual Funds and Bonds. HBID and HSBC Group (HSBC Holdings Plc and its subsidiaries and associates company or any of its branches) do not guarantee the underlying investment, principal or return on customer’s investment. You must read and understand the investment policy of each investment product to see if a product contains ESG and sustainability elements and is classified as an ESG and sustainable investment. Investment in Mutual Funds and Bonds are not covered by the deposit insurance program of the Indonesian Deposit Insurance Corporation (“LPS”).
Important information on ESG and sustainable investing
Today we finance a number of industries that significantly contribute to greenhouse gas emissions. We have a strategy to help our customers to reduce their emissions and to reduce our own. For more information visit www.hsbc.com/sustainability.
In broad terms “ESG and sustainable investing” products include investment approaches or instruments which consider environmental, social, governance and/or other sustainability factors to varying degrees. Certain instruments we classify as sustainable may be in the process of changing to deliver sustainability outcomes. There is no guarantee that ESG and Sustainable investing products will produce returns similar to those which don’t consider these factors. ESG and Sustainable investing products may diverge from traditional market benchmarks. In addition, there is no standard definition of, or measurement criteria for, ESG and Sustainable investing or the impact of ESG and Sustainable investing products. ESG and Sustainable investing and related impact measurement criteria are (a) highly subjective and (b) may vary significantly across and within sectors.
HSBC may rely on measurement criteria devised and reported by third party providers or issuers. HSBC does not always conduct its own specific due diligence in relation to measurement criteria. There is no guarantee: (a) that the nature of the ESG / sustainability impact or measurement criteria of an investment will be aligned with any particular investor’s sustainability goals; or (b) that the stated level or target level of ESG / sustainability impact will be achieved. ESG and Sustainable investing is an evolving area and new regulations are being developed which will affect how investments can be categorised or labelled. An investment which is considered to fulfil sustainable criteria today may not meet those criteria at some point in the future.
THE CONTENTS OF THIS DOCUMENT OR VIDEO HAVE NOT BEEN REVIEWED BY ANY REGULATORY AUTHORITY IN HONG KONG OR ANY OTHER JURISDICTION. YOU ARE ADVISED TO EXERCISE CAUTION IN RELATION TO THE INVESTMENT AND THIS DOCUMENT OR VIDEO. IF YOU ARE IN DOUBT ABOUT ANY OF THE CONTENTS OF THIS DOCUMENT OR VIDEO, YOU SHOULD OBTAIN INDEPENDENT PROFESSIONAL ADVICE.
© Copyright 2026. The Hongkong and Shanghai Banking Corporation Limited, ALL RIGHTS RESERVED.
No part of this document or video may be reproduced, stored in a retrieval system, or transmitted, on any form or by any means, electronic, mechanical, photocopying, recording or otherwise, without the prior written permission of The Hongkong and Shanghai Banking Corporation Limited.